Market Overview: Defining the Food And Beverage Stores Market landscape
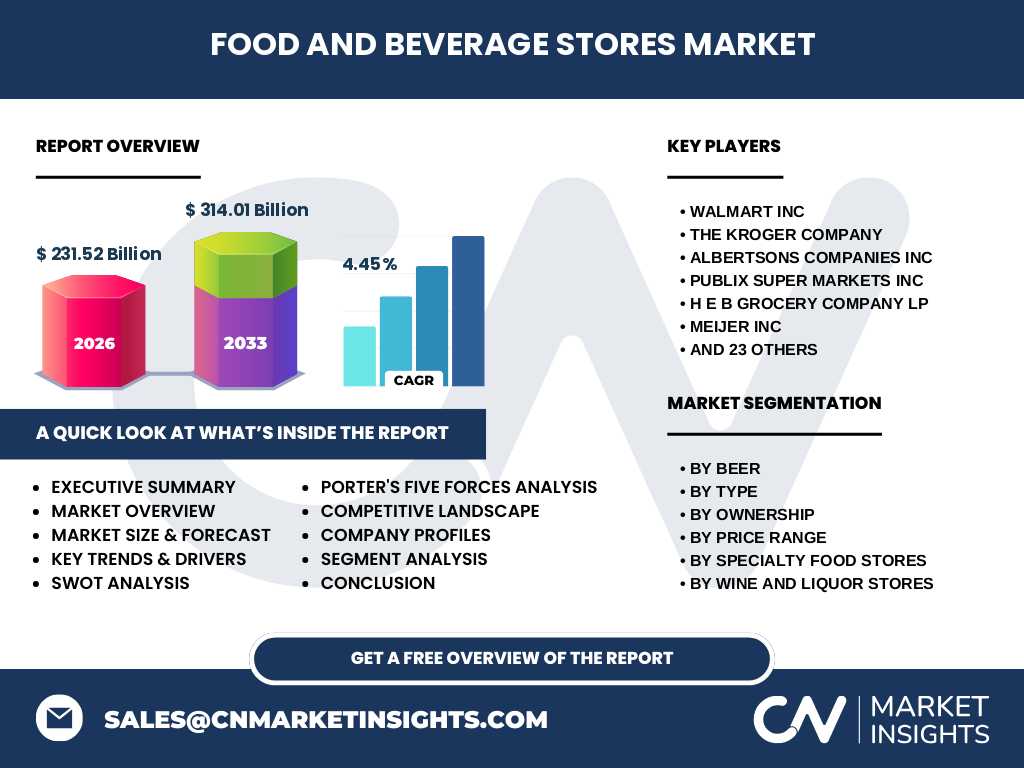
The Food And Beverage Stores Market encompasses brick-and-mortar and digital retail outlets specializing in grocery, specialty foods, and alcoholic beverages. With a 2026 market size of 231.52 Billion, this sector acts as the critical bridge between raw agricultural supply chains and end-consumer demand, playing a vital role in global food security and logistical distribution networks.
Structural Growth Drivers, Restraints, and Challenges
Growth is primarily driven by urbanization and the rising demand for specialty food stores. Conversely, the industry faces significant pressure from volatile raw material costs and supply chain disruptions at major ports. Regulatory bodies like the FDA and EFSA impose stringent compliance requirements, creating high barriers to entry for smaller independent retailers, particularly in cold-chain logistics.
The Shift Toward Niche Consumption Patterns
We are witnessing a profound shift toward health-conscious retail, with organic, gluten-free, and vegan/vegetarian segments gaining substantial momentum. Our analysis indicates that consumers now prioritize transparency in sourcing, forcing legacy retailers like Sprouts Farmers Market Inc and Whole Foods to innovate their inventory management to better cater to these rapidly expanding, high-margin product categories.
COVID-19 Impact and Long-term Recovery Analysis
The pandemic acted as a catalyst for digital transformation, forcing rapid adoption of click-and-collect and home delivery models. While initial supply shocks caused temporary instability, the Food And Beverage Stores Market recovered through accelerated automation in inventory tracking. Major players like Tesco plc and Kroger successfully leveraged these technological investments to ensure sustained resilience against future systemic disruptions.
Competitive Benchmarking and Strategic Dynamics
The landscape is dominated by heavyweights including Walmart Inc, Schwarz Group, and Costco Wholesale Corporation. Market concentration remains high, yet niche agility allows retailers like Wegmans Food Markets Inc to thrive. Strategic dynamics currently favor firms capable of integrating omnichannel retail with deep, localized supply chain relationships, effectively squeezing margins for less sophisticated independent players.
Executive Summary: High-Level Synthesis
The Food And Beverage Stores Market is poised for steady expansion, growing from 231.52 Billion in 2026 to 314.01 Billion by 2033. This 4.45% CAGR reflects a robust transition toward diversified retail formats. Success is no longer purely scale-based; rather, it hinges on operational excellence in inventory turnover and the ability to capture premium pricing within specialized wine and liquor or natural food segments.
Market Forecast: 2027 to 2033 Projections
Based on current macro indicators, the market trajectory is set for a compound annual growth rate of 4.45%, reaching 314.01 Billion by 2033. This growth is underpinned by sustained discretionary spending in premium food categories and the expansion of private-label brands across European and North American retail chains, signaling a shift toward higher value-added service models in the coming decade.
Segmentation Analysis: Understanding Market Dynamics
Segmentation is analyzed by type (specialty food, beer, liquor), ownership (retail chain vs. independent), and price range. Specialty food stores, particularly organic and gourmet outlets, act as growth accelerators. Meanwhile, the beer segment—divided into craft, import, and domestic—provides stable, high-volume recurring revenue, essential for balancing the thinner margins typically found in staple grocery commodities.
Regional Market Analysis: Geographic Performance
North America and Europe currently represent the most mature markets, characterized by high retail chain saturation. Conversely, the Asia-Pacific region, led by firms like Seven and i Holdings Co Ltd and Aeon Co Ltd, is witnessing explosive growth due to shifting demographic profiles. Logistical hurdles, such as cold-storage availability, remain the primary factor differentiating regional growth rates in these high-potential emerging economies.
In-depth Regional Review: Key Geographic Markets
In Europe, the REWE Group and Carrefour SA define the landscape, navigating complex cross-border regulatory frameworks. In North America, Publix Super Markets Inc and HEB exemplify regional dominance, utilizing local supply chain integration to fend off national competition. The data highlights that winners in these regions are those who effectively manage localized sourcing to minimize transit-related spoilage and inventory shrinkage.
Company Profiles: Strategic Positioning of Industry Leaders
Leading companies like Koninklijke Ahold Delhaize NV and ICA Gruppen AB are pivoting toward sustainable retail practices. We observe Costco Wholesale Corporation maintaining its unique value proposition through membership-based loyalty, while Tesco plc focuses on data-driven loyalty programs. Each player is strategically aligning their physical footprint with advanced e-commerce logistics to capture market share in both suburban and urban centers.
Porter's Five Forces Analysis
The Food And Beverage Stores Market faces intense competitive rivalry and moderate threat of substitution from meal-kit services. While buyer power is high due to price sensitivity, supplier power remains constrained by the sheer scale of global retailers. Overall, the ability to control private-label supply chains serves as a primary defensive moat, mitigating the pressure from industry-wide retail price volatility.
SWOT Analysis: Strategic Industry Insights
Strengths include high demand elasticity for essential goods and established distribution networks. Weaknesses involve razor-thin margins and exposure to labor shortages. Opportunities lie in digital integration and personalized nutrition, while Threats include unpredictable climate impacts on raw ingredients and stringent trade regulations. Mastering this balance is critical for maintaining long-term institutional performance in this 300-billion-plus sector.
Value Chain Analysis: From Raw Materials to End-Users
The value chain begins with agricultural producers and distributors, flows through regional logistics hubs, and concludes at the retail storefront. Value creation is maximized at the retail interface, where retailers like Wegmans or Whole Foods provide curation and quality assurance. Efficiencies in this chain are largely determined by inventory management technology that reduces lead times and minimizes wastage of perishable goods.
Investment Insights and Strategic Recommendations
Investors should focus on firms exhibiting high operating leverage through technological adoption, specifically those integrating AI-driven demand forecasting. High-potential areas include organic food stores and craft beer retail, where premium pricing maintains healthy margins. Furthermore, investments in retailers that successfully manage the transition to zero-waste logistics are likely to outperform the broader market as regulatory pressures on carbon emissions intensify.
Conclusion and Key Takeaways
The transition to a 314.01 Billion market by 2033 underscores the resilience and evolution of the Food And Beverage Stores Market. Success requires a dual-track strategy: maintaining operational efficiency in traditional brick-and-mortar retail while aggressively capturing the digital-first consumer through personalized specialty food offerings and streamlined delivery channels. Adaptability remains the primary determinant of long-term survival.
Research Methodology: Triangulating Baseline Estimates
Our analysis employs a robust triangulation methodology. We integrate official trade registry data, proprietary primary stakeholder interviews with retail supply chain directors, and secondary macroeconomic indicators. These data points are stress-tested against industry-specific reports from regulatory bodies and customs data, ensuring the 4.45% CAGR estimate accurately reflects both historical performance and future market-shifting variables.
Scope of the Report: Coverage and Limitations
This report covers the global Food And Beverage Stores Market, including specialty food, liquor, and grocery chains. Limitations include the exclusion of restaurant-based food services and informal street markets. The report focuses on formal retail entities with physical and digital presence, providing a comprehensive assessment of the economic and logistical forces currently shaping the modern retail landscape through 2033.
Recent Developments: Market Movements and Partnerships
Recent activity highlights significant M&A consolidation, as major chains seek to bolster their logistics capabilities. Partnerships between retailers and fintech providers for seamless payment, as well as joint ventures with cold-chain technology firms, represent the current standard for strategic growth. These moves demonstrate that industry leaders are prioritizing operational agility to navigate shifting consumer preferences and localized regulatory hurdles.